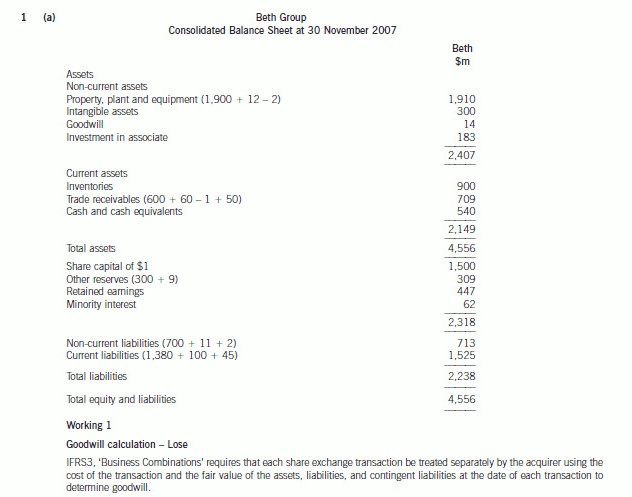
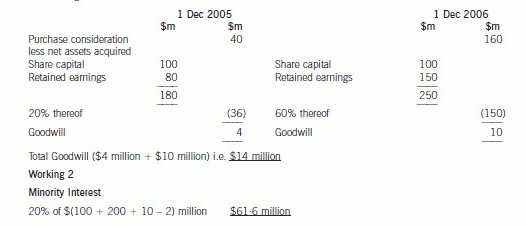
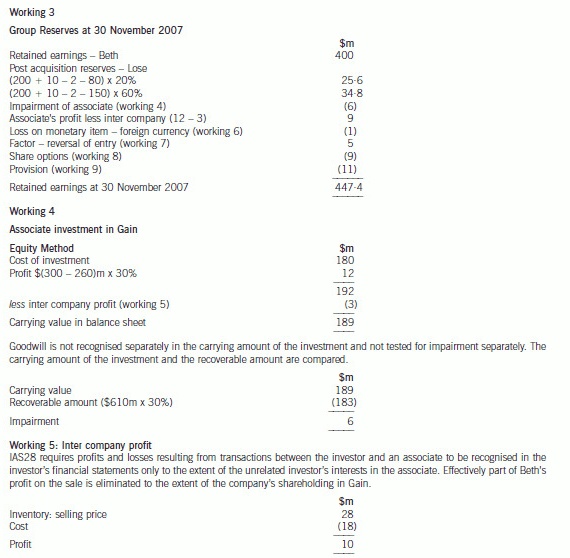
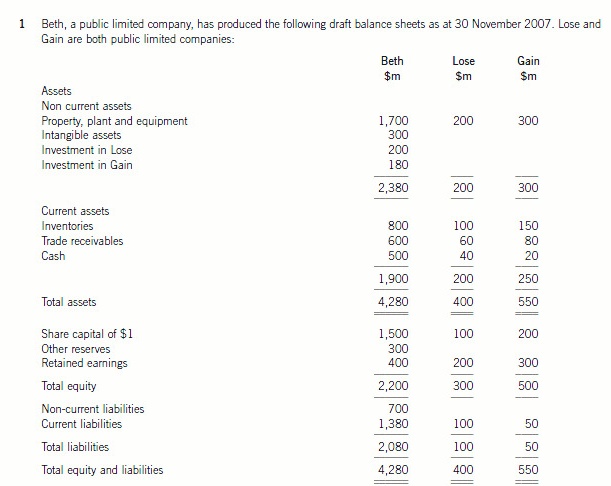
1 Beth,a public limited company,has produced the following draft balance sheets as at 30 November 2007 .Lose and-|||-Gain are both public limited companies:-|||-Beth Lose Gain-|||- -|||-Assets-|||-Non current assets-|||-Property, plant and equipment-|||-Intangible assets-|||-Investment in Lose-|||-Investment in Gain-|||-1,700-|||-300-|||-200-|||-180-|||-2,380-|||-200-|||-__-|||-200-|||-300-|||-__-|||-300-|||-Current assets-|||-Inventories-|||-Trade receivables-|||-Cash-|||-Total assets-|||-800-|||-600-|||-500-|||-1,900-|||-4,280-|||-60-|||-dfrac (40)(200)-|||-dfrac (150)(80)-|||-20-|||-250/55020/250-|||-100-|||-Share capital of https:/img.cdnjtzy.com/zyb_5060082af340502371cb72efa6c64eb4.jpg-|||-Other reserves-|||-1,500-|||-300-|||-400-|||-2,200-|||-dfrac (200)(300)-|||-dfrac (300)(500)-|||-Retained earnings-|||-Total equity-|||-Non-currentliabilities-|||-700-|||-Current liabilities-|||-Total liabilities-|||-2,080-|||-4,280-|||-100/100-|||-400-|||-dfrac (50)(50)-|||-Total equity and liabilities1 Beth,a public limited company,has produced the following draft balance sheets as at 30 November 2007 .Lose and-|||-Gain are both public limited companies:-|||-Beth Lose Gain-|||- -|||-Assets-|||-Non current assets-|||-Property, plant and equipment-|||-Intangible assets-|||-Investment in Lose-|||-Investment in Gain-|||-1,700-|||-300-|||-200-|||-180-|||-2,380-|||-200-|||-__-|||-200-|||-300-|||-__-|||-300-|||-Current assets-|||-Inventories-|||-Trade receivables-|||-Cash-|||-Total assets-|||-800-|||-600-|||-500-|||-1,900-|||-4,280-|||-60-|||-dfrac (40)(200)-|||-dfrac (150)(80)-|||-20-|||-250/55020/250-|||-100-|||-Share capital of https:/img.cdnjtzy.com/zyb_226802f0ed3ad10da35b751f6d23bdcd.jpg-|||-Other reserves-|||-1,500-|||-300-|||-400-|||-2,200-|||-dfrac (200)(300)-|||-dfrac (300)(500)-|||-Retained earnings-|||-Total equity-|||-Non-currentliabilities-|||-700-|||-Current liabilities-|||-Total liabilities-|||-2,080-|||-4,280-|||-100/100-|||-400-|||-dfrac (50)(50)-|||-Total equity and liabilitiesLose and Gain have not issued any share capital since the acquisition of the shareholdings by Beth. The fairvalues of the net assets of Lose and Gain were the same as their carrying amounts at the date of the acquisitions.Beth did not have significant influence over Lose at any time before gaining control of Lose, but does havesignificant influence over Gain. There has been no impairment of goodwill on the acquisition of Lose since itsacquisition, but the recoverable amount of the net assets of Gain has been deemed to be 610 million at30 November 2007.(ii) Lose entered into an operating lease for a building on 1 December 2006. The building was converted into officespace during the year at a cost to Lose of 10 million. The operating lease is for a period of six years, at the endof which the building must be returned to the lessor in its original condition. Lose thinks that it would cost2 million to convert the building back to its original condition at prices at 30 November 2007. The entries thathad been made in the financial statements of Lose were the charge for operating lease rentals (4 million perannum) and the improvements to the building. Both items had been charged to the income statement. Theimprovements were completed during the financial year.(iii) On 1 October 2007, Beth sold inventory costing 18 million to Gain for 28 million. At 30 November 2007,the inventory was still held by Gain. The inventory was sold to a third party on 15 December 2007 for35 million.(iv) Beth had contracted to purchase an item of plant and equipment for 12 million euros on the following terms:Payable on signing contract (1 September 2007) 50%Payable on delivery and installation (11 December 2007) 50%The amount payable on signing the contract (the deposit) was paid on the due date and is refundable. Thefollowing exchange rates are relevant:2007 Euros to 1 dollar1 September 0·7530 November 0·8511 December 0·79The deposit is included in trade receivables at the rate of exchange on 1 September 2007. A full year’s chargefor depreciation of property, plant and equipment is made in the year of acquisition using the straight line methodover six years.(v) Beth sold some trade receivables which arose during November 2007 to a factoring company on 30 November2007. The trade receivables sold are unlikely to default in payment based on past experience but they are longdated with payment not due until 1 June 2008. Beth has given the factor a guarantee that it will reimburse anyamounts not received by the factor. Beth received 45 million from the factor being 90% of the trade receivablessold. The trade receivables are not included in the balance sheet of Beth and the balance not received from thefactor (10% of the trade receivables factored) of 5 million has been written off against retained earnings.(vi) Beth granted 200 share options to each of its 10,000 employees on 1 December 2006. The shares vest if theemployees work for the Group for the next two years. On 1 December 2006, Beth estimated that there would be1,000 eligible employees leaving in each year up to the vesting date. At 30 November 2007, 600 eligibleemployees had left the company. The estimate of the number of employees leaving in the year to 30 November2008 was 500 at 30 November 2007. The fair value of each share option at the grant date (1 December 2006)was 10. The share options have not been accounted for in the financial statements.(vii) The Beth Group operates in the oil industry and contamination of land occurs including the pollution of seas andrivers. The Group only cleans up the contamination if it is a legal requirement in the country where it operates.The following information has been produced for Beth by a group of environmental consultants for the year ended30 November 2007:Cost to clean up contamination Law existing in country m 5 No 7 To come into force in December 2007 4 YesThe directors of Beth have a widely publicised environmental attitude which shows little regard to the effects onthe environment of their business. The Group does not currently produce a separate environmental report and noprovision for environmental costs has been made in the financial statements. Any provisions would be shown asnon-current liabilities. Beth is likely to operate in these countries for several years.4Other informationBeth is currently suffering a degree of stagnation in its business development. Its domestic and international marketsare being maintained but it is not attracting new customers. Its share price has not increased whilst that of itscompetitors has seen a rise of between 10% and 20%. Additionally it has recently received a significant amount ofadverse publicity because of its poor environmental record and is to be investigated by regulators in several countries.Although Beth is a leading supplier of oil products, it has never felt the need to promote socially responsible policiesand practices or make positive contributions to society because it has always maintained its market share. It isrenowned for poor customer support, bearing little regard for the customs and cultures in the communities where itdoes business. It had recently made a decision not to pay the amounts owing to certain small and medium entities(SMEs) as the directors feel that SMEs do not have sufficient resources to challenge the non-payment in a court oflaw. The management of the company is quite authoritarian and tends not to value employees’ ideas andcontributions.Required:(a) Prepare the consolidated balance sheet of the Beth Group as at 30 November 2007 in accordance withInternational Financial Reporting Standards. (35 marks)
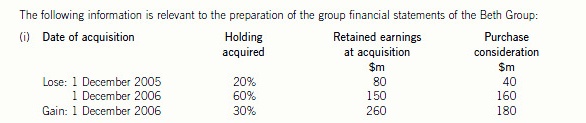
Lose and Gain have not issued any share capital since the acquisition of the shareholdings by Beth. The fair
values of the net assets of Lose and Gain were the same as their carrying amounts at the date of the acquisitions.
Beth did not have significant influence over Lose at any time before gaining control of Lose, but does have
significant influence over Gain. There has been no impairment of goodwill on the acquisition of Lose since its
acquisition, but the recoverable amount of the net assets of Gain has been deemed to be $610 million at
30 November 2007.
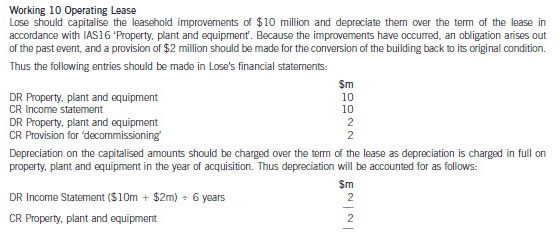
(ii) Lose entered into an operating lease for a building on 1 December 2006. The building was converted into office
space during the year at a cost to Lose of $10 million. The operating lease is for a period of six years, at the end
of which the building must be returned to the lessor in its original condition. Lose thinks that it would cost
$2 million to convert the building back to its original condition at prices at 30 November 2007. The entries that
had been made in the financial statements of Lose were the charge for operating lease rentals ($4 million per
annum) and the improvements to the building. Both items had been charged to the income statement. The
improvements were completed during the financial year.
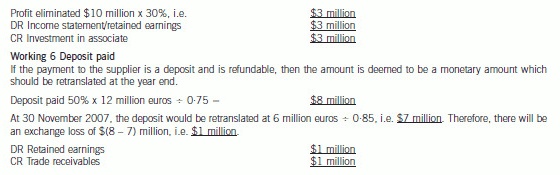
(iii) On 1 October 2007, Beth sold inventory costing $18 million to Gain for $28 million. At 30 November 2007,
the inventory was still held by Gain. The inventory was sold to a third party on 15 December 2007 for
$35 million.
(iv) Beth had contracted to purchase an item of plant and equipment for 12 million euros on the following terms:
Payable on signing contract (1 September 2007) 50%
Payable on delivery and installation (11 December 2007) 50%
The amount payable on signing the contract (the deposit) was paid on the due date and is refundable. The
following exchange rates are relevant:
2007 Euros to 1 dollar
1 September 0·75
30 November 0·85
11 December 0·79
The deposit is included in trade receivables at the rate of exchange on 1 September 2007. A full year’s charge
for depreciation of property, plant and equipment is made in the year of acquisition using the straight line method
over six years.
(v) Beth sold some trade receivables which arose during November 2007 to a factoring company on 30 November
2007. The trade receivables sold are unlikely to default in payment based on past experience but they are long
dated with payment not due until 1 June 2008. Beth has given the factor a guarantee that it will reimburse any
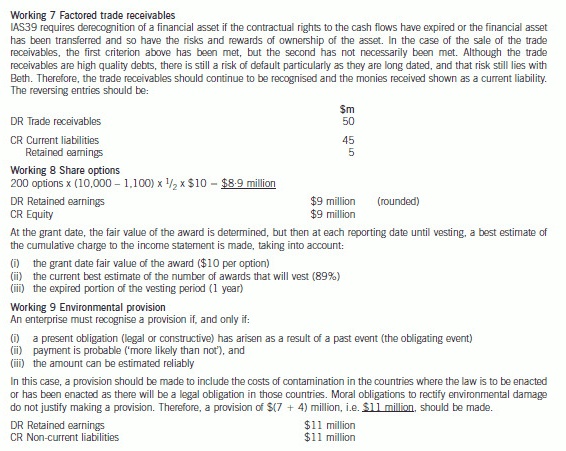
amounts not received by the factor. Beth received $45 million from the factor being 90% of the trade receivables
sold. The trade receivables are not included in the balance sheet of Beth and the balance not received from the
factor (10% of the trade receivables factored) of $5 million has been written off against retained earnings.
(vi) Beth granted 200 share options to each of its 10,000 employees on 1 December 2006. The shares vest if the
employees work for the Group for the next two years. On 1 December 2006, Beth estimated that there would be
1,000 eligible employees leaving in each year up to the vesting date. At 30 November 2007, 600 eligible
employees had left the company. The estimate of the number of employees leaving in the year to 30 November
2008 was 500 at 30 November 2007. The fair value of each share option at the grant date (1 December 2006)
was $10. The share options have not been accounted for in the financial statements.
(vii) The Beth Group operates in the oil industry and contamination of land occurs including the pollution of seas and
rivers. The Group only cleans up the contamination if it is a legal requirement in the country where it operates.
The following information has been produced for Beth by a group of environmental consultants for the year ended
30 November 2007:
Cost to clean up contamination Law existing in country
$m
5 No
7 To come into force in December 2007
4 Yes
The directors of Beth have a widely publicised environmental attitude which shows little regard to the effects on
the environment of their business. The Group does not currently produce a separate environmental report and no
provision for environmental costs has been made in the financial statements. Any provisions would be shown as
non-current liabilities. Beth is likely to operate in these countries for several years.
4
Other information
Beth is currently suffering a degree of stagnation in its business development. Its domestic and international markets
are being maintained but it is not attracting new customers. Its share price has not increased whilst that of its
competitors has seen a rise of between 10% and 20%. Additionally it has recently received a significant amount of
adverse publicity because of its poor environmental record and is to be investigated by regulators in several countries.
Although Beth is a leading supplier of oil products, it has never felt the need to promote socially responsible policies
and practices or make positive contributions to society because it has always maintained its market share. It is
renowned for poor customer support, bearing little regard for the customs and cultures in the communities where it
does business. It had recently made a decision not to pay the amounts owing to certain small and medium entities
(SMEs) as the directors feel that SMEs do not have sufficient resources to challenge the non-payment in a court of
law. The management of the company is quite authoritarian and tends not to value employees’ ideas and
contributions.
Required:
(a) Prepare the consolidated balance sheet of the Beth Group as at 30 November 2007 in accordance with
International Financial Reporting Standards. (35 marks)
题目解答
答案